A seller's net proceeds calculation is the precise accounting of what you will actually receive at closing after every payoff, fee, tax, and concession has been subtracted from the contract price. The governing formula is straightforward: sale price − mortgage payoff − agent commissions − closing costs − prorations − seller concessions − other liens = net proceeds. According to Investopedia, if that result turns negative, the seller must cover the shortfall out of pocket or pursue a short sale. The figure you see on your net sheet is an estimate; the Closing Disclosure issued at least three business days before closing is the authoritative, final reconciliation.
Two cost categories tend to dominate the calculation. Agent commissions commonly total 5%–6% of the sale price when both sides' fees are combined, making them the single largest deduction for most resale transactions. Seller-paid closing costs beyond commissions often represent a noticeable portion of the loan amount, covering title fees, transfer taxes, escrow charges, recording fees, and prorated expenses. Verify your mortgage payoff statement and all prorations with your lender and title company before you rely on any estimate.
Key Takeaways
A seller's net proceeds equal the contract sale price minus every payoff, commission, fee, proration, and concession, with the Closing Disclosure serving as the final, authoritative reconciliation of that figure.
| Point | Details |
|---|---|
| The core formula | Sale price minus mortgage payoff, commissions, closing costs, prorations, and concessions equals net proceeds. |
| Largest deductions | Mortgage payoff and agent commissions (commonly 5%–6% of sale price) typically account for the majority of reductions. |
| Closing Disclosure is final | The Closing Disclosure, issued at least three business days before closing, is the only authoritative reconciliation of estimated versus actual proceeds. |
| Verify payoffs early | Obtain a formal lender payoff statement valid through the closing date; a mortgage statement balance is not sufficient. |
| Yhluxrealestate's role | Yhluxrealestate prepares verified, line-item net sheets and coordinates with title and escrow to reconcile the Closing Disclosure before closing. |
Table of Contents
- What does a seller's net proceeds calculation include?
- How do you calculate net proceeds step by step?
- Which online calculators help you estimate net proceeds?
- How do taxes affect your net proceeds from a home sale?
- How do state and local rules change what you net?
- What mistakes cost sellers the most at closing?
- Why an experienced listing agent protects your net proceeds
- Yhluxrealestate prepares your net sheet with verified numbers
- Sources
- FAQ
What does a seller's net proceeds calculation include?
Every dollar that leaves your side of the closing table reduces your net proceeds. Understanding each line item before you sit down with a net-sheet calculator is what separates a seller who is pleasantly surprised from one who is not.
Mortgage payoff. The outstanding principal balance plus accrued interest to the estimated closing date. Interest accrues daily, so a closing date change of even a week shifts this figure.
Title and settlement fees. Charges from the title company or settlement attorney for examining title, issuing title insurance, and coordinating the closing. These vary by state and provider.
Transfer taxes. State and county taxes assessed on the transfer of real property. In some jurisdictions the seller pays; in others the cost is split or assigned to the buyer.
Recording fees. Charged by the county recorder to officially record the deed and any lien releases.
Prorated property taxes. If you have paid taxes in advance, you may receive a credit; if taxes are paid in arrears (as in most states), you will owe a debit for the portion of the year you owned the home.
Prorated HOA dues. Similar logic applies: dues paid ahead generate a credit; unpaid dues or special assessments are debited.
Seller concessions and repair credits. Any amount you agreed to pay toward the buyer's closing costs or repairs is a dollar-for-dollar reduction of your proceeds.
Other liens. Second mortgages, home equity lines of credit (HELOCs), mechanic's liens, or judgment liens must all be paid from proceeds before you receive anything.
Attorney fees. Required in some states (New York, Georgia, South Carolina, among others) and optional in others.
Home warranty. If you offered the buyer a one-year home warranty as a selling incentive, that premium is deducted at closing.
Staging and pre-sale repair costs. Paid before closing but properly included in your net-proceeds estimate to understand true profitability.
To assemble accurate inputs, gather your most recent mortgage statement, a formal payoff quote from your lender (valid through your anticipated closing date), your HOA ledger, the most recent property tax bill, and any repair invoices or concession agreements documented in the contract.
How do you calculate net proceeds step by step?
Bankrate's subtraction model frames the calculation cleanly: start with the contract price and subtract every cost in sequence. The five steps below follow that logic and close with a worked example.
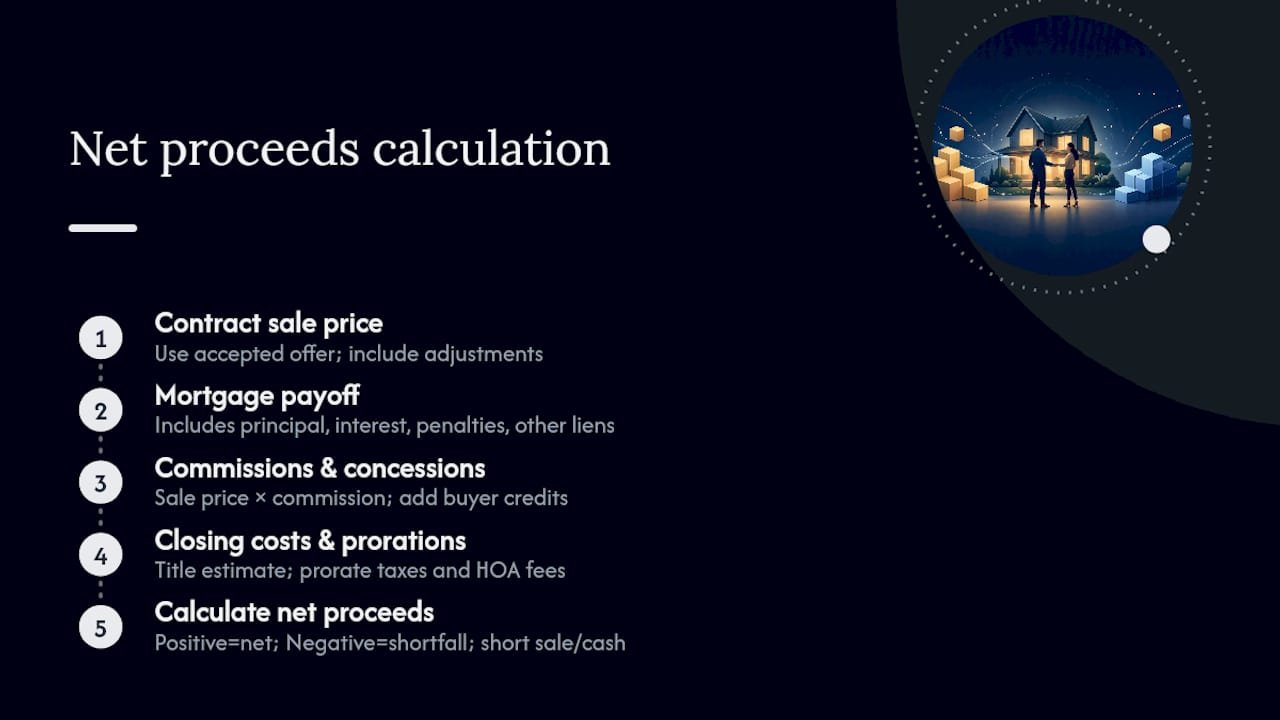
Step 1: Confirm the contract sale price. Use the accepted offer price, not the list price. Any price adjustments negotiated after inspection must be reflected here.
Step 2: Obtain a formal mortgage payoff statement. Call your lender and request a payoff quote good through a date five to seven days past your anticipated closing. The quote will include principal, accrued interest, and any prepayment penalties. Add payoffs for any second mortgage, HELOC, or other liens.
Step 3: Calculate commissions and concessions. Multiply the sale price by the agreed commission rate. Add any buyer concessions or repair credits documented in the contract.
Step 4: Estimate closing costs, transfer taxes, and prorations. Your title company can provide a preliminary seller-side estimate. Use your property tax bill and HOA statement to calculate prorations to the closing date.
Step 5: Subtract and interpret. If the result is positive, that is your estimated net. If negative, you are underwater; options include negotiating a short sale with your lender or bringing cash to closing.
Pro Tip: Request a payoff statement that extends five to seven days beyond your target closing date. Closing delays are common, and a payoff that expires before you close forces a second request, which can slow disbursement.
Worked example: $650,000 sale in Nevada
The Closing Disclosure, received no later than three business days before closing, will reconcile every one of these figures against the final, lender-verified amounts. A closing date that shifts by two weeks, for instance, adds roughly two weeks of mortgage interest to the payoff and adjusts prorations accordingly.
Which online calculators help you estimate net proceeds?
Several reputable tools allow sellers to model their net proceeds before a formal net sheet is produced. Each has genuine utility and genuine limits.
Bankrate's home-sale net proceeds calculator walks through the subtraction model described above, prompting for sale price, mortgage balance, commission rate, and estimated closing costs. It is well-suited for a first-pass estimate.
Zillow's seller closing cost calculator incorporates state-level transfer tax and title insurance norms, making it more geographically sensitive than a generic tool.
The RPR (Realtors Property Resource) Seller's Net Sheet, available to licensed agents through the RPR platform, produces a detailed, agent-branded net sheet that accounts for local title and escrow practices. Sellers benefit from this tool when their agent runs it on their behalf with verified inputs.
Independence Title's Sellers Net Sheet and similar title-company calculators are particularly useful because they incorporate the company's own fee schedule, reducing one major source of estimation error.
The Florida Department of Revenue's transfer tax tables and comparable state resources are worth consulting directly when your state's transfer tax is a meaningful line item.
Before entering numbers into any calculator, assemble this input checklist:
- Accepted contract sale price
- Formal mortgage payoff amount (with expiration date)
- Commission rate as agreed in the listing agreement
- Estimated closing date
- Most recent annual property tax bill
- HOA monthly dues and any outstanding special assessments
- Agreed seller concessions from the contract addenda
- Any known second liens or HELOC balances
The critical limitation of automated calculators is that they estimate. County-specific fees, title insurance premiums that vary by provider, and interest accrual to an exact closing date cannot be computed precisely without a formal payoff statement and a title company's fee schedule. Treat any calculator result as a planning figure, not a closing guarantee. When the sale price is high or the transaction is complex, ask your title or escrow company for a formal seller-side closing cost estimate before you finalize your pricing strategy.
How do taxes affect your net proceeds from a home sale?
Net proceeds and taxable gain are not the same figure, a distinction that surprises many sellers. Your net proceeds are the cash you receive; your taxable gain is calculated separately as net proceeds minus your adjusted basis in the property (original purchase price plus capital improvements, minus depreciation if applicable).
IRS Topic 701 governs the tax treatment of home sales and outlines the conditions under which a seller may exclude up to $250,000 of gain ($500,000 for married couples filing jointly) from federal income tax. To qualify for the primary residence exclusion, you generally must have owned and used the home as your principal residence for at least two of the five years preceding the sale.
The IRS primary residence exclusion is one of the most valuable provisions in the tax code for individual sellers, but it carries conditions that must be verified before closing — particularly if the home was rented, used as a vacation property, or owned for fewer than two years. Sellers who do not meet the ownership and use tests may owe capital gains tax on the full gain, at rates that vary by income and holding period.
When to consult a tax professional:
- The gain exceeds the exclusion threshold ($250,000 single / $500,000 married filing jointly)
- The property was an investment or rental at any point during ownership
- You have a "nonqualified use" period (time the home was not your primary residence)
- The sale involves a 1031 exchange or installment sale structure
- You are a nonresident alien seller (FIRPTA withholding rules apply)
The Closing Disclosure you receive before closing will document the gross proceeds reported to the IRS on Form 1099-S. Your tax professional uses that figure, combined with your adjusted basis, to calculate the reportable gain on Schedule D.
How do state and local rules change what you net?
Transfer taxes, title insurance customs, and escrow practices vary enough by state and county that two sellers with identical sale prices can walk away with meaningfully different net proceeds simply because of geography.
A few concrete illustrations:
- Nevada (including Clark County, where Las Vegas sits) imposes a real property transfer tax assessed at $1.95 per $500 of value, paid by the seller. On a $650,000 sale, that is $1,950 — a modest but real deduction.
- New York levies a transfer tax of 0.4% of the sale price statewide, with New York City adding its own mansion tax on properties above $1 million, which can reach 3.9% on sales above $25 million.
- Florida charges a documentary stamp tax of $0.70 per $100 of the sale price (Miami-Dade uses a different rate structure), typically paid by the seller.
- California imposes a county transfer tax of $1.10 per $1,000 of value, with many cities layering additional transfer taxes on top.
Title insurance customs shift costs further. In most of the western United States, including Nevada, the seller customarily pays for the owner's title policy. In many northeastern states, the buyer pays. Zillow's closing cost data confirms that these regional norms materially affect which fees appear on the seller's side of the ledger.
The practical action item: call your local title company or county recorder's office early in the listing process, before you price the home, to confirm which fees are assessed to the seller in your specific county. An early title estimate from the RPR Seller's Net Sheet or your title company avoids late-stage adjustments that compress your net.
What mistakes cost sellers the most at closing?
The most consequential errors in net-proceeds estimation are not mathematical; they are errors of omission, where sellers simply forget a line item or accept a stale figure.
Using list price instead of contract price. Net proceeds flow from the accepted offer, not the asking price. A seller who mentally banks the list price and then accepts an offer $20,000 below it has already miscalculated before the first deduction.
Ignoring prorations. Property taxes paid in arrears mean the seller owes the buyer a credit for the portion of the year the seller owned the home. On a $650,000 property with a $7,000 annual tax bill, a mid-year closing generates a proration credit to the buyer of roughly $3,500.
Relying on a mortgage statement balance rather than a payoff quote. Your statement balance does not include interest accrued since the last payment or any prepayment fees. A formal payoff statement from your lender, valid through the closing date, is the only accurate figure.
Forgetting HOA payoffs and special assessments. Many HOAs require a transfer fee, a resale certificate fee, and full payment of any outstanding special assessments before they will issue a clearance letter. These can total several thousand dollars on luxury properties.
Underestimating concessions. Seller concessions reduce proceeds dollar-for-dollar. A $10,000 repair credit negotiated after inspection is $10,000 less in your pocket, not a vague "discount."
Pro Tip: Document every concession in a signed contract addendum before closing. Verbal agreements about repair credits or closing cost contributions that are not in writing can be disputed at the closing table, creating delays and potential legal exposure.
Short-sale considerations deserve a separate note. If your payoff obligations exceed the sale price, your lender must agree to accept less than the full amount owed. Short sales require lender approval, take considerably longer to close than standard transactions, and may carry tax consequences of their own — the forgiven debt can be treated as income under certain circumstances, though IRS exclusions may apply.
Why an experienced listing agent protects your net proceeds
The contract price a skilled listing agent negotiates is only one dimension of what an agent contributes to a seller's final cash position. The more nuanced value lies in the precision of the net sheet, the management of concessions, and the timing of the close.
Sellers who receive a detailed, line-item net sheet at the outset of the listing process make better decisions about pricing, repairs, and concession strategy. An agent who runs the numbers with a verified payoff statement and a title company's fee schedule — rather than a back-of-envelope estimate — gives you a planning figure you can actually rely on. The difference between a rough estimate and a verified one can be $15,000 or more on a luxury transaction, particularly when transfer taxes, HOA special assessments, and seller-paid title policies are in play.
The staging versus repair calculus is another area where practitioner experience pays dividends. A $5,000 staging investment on a luxury property often yields a price premium that far exceeds the cost; a $15,000 repair demanded by a buyer after inspection may be negotiable to a $7,500 credit if the agent understands the local market's tolerance for as-is pricing. Neither decision is obvious without a current, accurate net sheet to model the outcome.
Sellers should provide their agent with the mortgage payoff statement, HOA ledger, most recent tax bill, and any repair invoices or pending assessments. In return, they should expect a detailed net sheet updated to reflect the accepted contract and a preview of the Closing Disclosure structure. Request that payoff verification occur seven to ten days before the scheduled closing date; that window allows time to correct errors before funds are disbursed.
Yhluxrealestate prepares your net sheet with verified numbers
Sellers who list with Yhluxrealestate receive a detailed, line-item seller net sheet prepared with verified payoff figures, confirmed title and escrow estimates, and a clear accounting of every concession and proration before they accept an offer. Yelena Horton's team coordinates directly with the title company and escrow officer to reconcile the preliminary net sheet against the Closing Disclosure, so there are no last-minute surprises compressing your proceeds.

To produce your custom net sheet, provide the accepted contract, your lender's payoff statement, HOA documentation, the most recent property tax bill, and any repair invoices or concession agreements. Yhluxrealestate's global network, backed by Sotheby's International Realty, also positions your property for maximum market exposure, which directly supports the contract price that anchors the entire calculation. Contact Yhluxrealestate to schedule a net-sheet consultation and walk through your Closing Disclosure before your listing goes live.
Sources
The following primary and authoritative sources are worth consulting directly as you assemble your net-proceeds estimate.
IRS Topic 701 (irs.gov/taxtopics/tc701) is the governing reference for home-sale tax treatment, including the primary residence exclusion conditions and the rules for calculating taxable gain. Consult it before assuming your gain is fully excludable.
Bankrate's net proceeds guide provides a clear worked example of the subtraction model and explains how commissions and mortgage payoffs interact with the final figure.
Investopedia's net proceeds explainer offers a concise definition and covers the short-sale scenario when proceeds turn negative.
LegalClarity's seller net proceeds article details the Closing Disclosure timeline, explains prorations and concessions, and provides practitioner-level guidance on reviewing the CD line by line before closing.
Zillow's seller closing costs page incorporates state-level transfer tax norms and title insurance customs, making it a useful reference for understanding geographic variation in seller costs.
The RPR Seller's Net Sheet tool (available through licensed agents) produces a detailed, locally calibrated net sheet that accounts for regional title and escrow practices.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- Net Proceeds Explained: Definition, Calculation, and Real-Life Examples
- Net proceeds from the sale of a house: How much do you really make?
- How to Calculate Seller Net Proceeds in a Home Sale - LegalClarity
- Irs
- Once you've accepted an offer on your home, you may be anticipating a nice profit. But then come all of the closing costs you’re expected to pay.
FAQ
What is the basic formula for calculating net proceeds?
Net proceeds equal the contract sale price minus the mortgage payoff, agent commissions, closing costs, prorations, seller concessions, and any other liens. The Closing Disclosure finalizes every figure at least three business days before closing.
How much does it typically cost to sell a $650,000 home?
What is the difference between net proceeds and taxable gain?
Net proceeds are the cash you receive after all costs; taxable gain is calculated separately as net proceeds minus your adjusted basis in the property. The IRS primary residence exclusion may shelter up to $250,000 (single) or $500,000 (married filing jointly) of that gain from federal income tax under IRS Topic 701.
When does a seller owe money at closing instead of receiving it?
If the total of the mortgage payoff, commissions, and closing costs exceeds the sale price, the seller's net proceeds are negative. The seller must either bring cash to closing to cover the shortfall or negotiate a short sale with the lender.
How do I get an accurate seller net sheet before closing?
Request a formal payoff statement from your lender, an HOA ledger, your most recent property tax bill, and a preliminary closing cost estimate from your title company. Provide those documents to your listing agent, who can produce a verified net sheet. Yhluxrealestate prepares these for sellers as part of its listing process.